

The ATO is writing to taxpayers who have varied their PAYG instalments to nil over multiple years, reminding them that the general interest charge (‘GIC’) may apply where their instalments have been significantly understated.
Where varied instalments are less than 85% of the total tax payable, the ATO may impose GIC on the difference and, depending on the circumstances, penalties may also be applied.
Taxpayers are advised to maintain appropriate records to support their variation decisions, and review variations where circumstances change.
Editor: Please contact our office if you need any assistance in this regard.
From 1 April 2027, employers will no longer be able to use the ‘otherwise deductible rule’ to reduce the taxable value of an expense payment fringe benefit provided to an employee where the expense is:
This includes where an employer pays for, or reimburses, work-related expenses, such as home office expenses, home phone or internet expenses, or self-education expenses.
However, the otherwise deductible rule can continue to apply where the expense is:
Further, from 1 April 2027, certain work-related items will no longer qualify for the FBT exemption where they are provided under a salary sacrifice arrangement. These include:
Eligible work-related items may still qualify for the exemption where they are not provided under a salary sacrifice arrangement.
Further, under the changes, employers may be able to provide an employee with more than one eligible work-related item in an FBT year, even where the items have the same or substantially identical function, and continue to receive the exemption where the items:
This repeals the general ‘one-item’ restriction applying to this work-related item exemption from 1 April 2027.
The ATO has highlighted several misconceptions that commonly lead to incorrect claims under the cents per kilometre method for claiming deductions for car expenses. Common errors include:
Editor: Trips can be recorded using the myDeductions tool in the ATO app. The app offers three tracking options: point-to-point, GPS and odometer.
From 1 July 2026, the $20,000 instant asset write-off has been made permanent for small businesses.
Businesses with an aggregated turnover of less than $10 million may be able to claim an immediate deduction for the business portion of an eligible depreciating asset costing less than $20,000 in the year the asset is first used or installed ready for use.
The re-introduced ‘loss carry back’ measure has also now become law, applying to income years starting on or after 1 July 2026.
Where eligible, companies will broadly be able to carry back a tax loss (revenue in nature) and apply it against tax paid in either, or both, of the previous two income years, basically giving rise to a tax refund for the loss year.
The ATO has reported that around 123,000 individuals have made ‘downsizer super contributions’ since the scheme commenced in 2018, contributing more than $31 billion to super funds.
Broadly, where the various requirements are satisfied, eligible individuals aged 55 years or older can contribute up to $300,000 from the sale of their home into super. Eligible couples may be able to contribute up to $600,000 combined.
The ATO is continuing its visa data-matching program, acquiring data from the Department of Home Affairs from the 2027 to the 2029 income years. Under this program, the data collected may include:
Data relating to around 9 million individuals is expected to be collected under this program each financial year.
The ATO is also continuing its passenger movements data-matching program for the same period.
Under this program, the data collected by the ATO may include names, dates of birth, arrival and departure dates, passport information and status types (including visa status, residency and citizenship status).
The ATO has updated its guidance on rental property income and expenses from 1 July 2026, including for properties that are also used as holiday homes.
Where a property is a holiday home, it must be used, or held for use, mainly to produce rental income before the owner can claim any expenses relating to its ownership and use.
If this requirement is not met, expenses that are entirely non-deductible may include:
Where the property is used mainly to produce rental income but there is some minor private use, such as a week or a few weekends in the off season when there are no bookings, ownership and use expenses must still be apportioned accurately to reflect the periods of private use.
The ATO is urging individuals to check whether they have lost or unclaimed super, with more than $21 billion waiting to be reunited with its owners.
Super can become lost when an account is inactive and the fund cannot contact the member, often following a change of job, address or phone number.
In some cases, the balance may be transferred to the ATO to hold until it can be reunited with the individual.
The ATO reports that last year, more than $1.1 billion was returned through consolidations and direct payments to eligible individuals.
ASIC has launched the Small Business Director Essentials hub, a new digital resource bringing together practical guidance, learning modules and tools in one place.
“The new Small Business Director Essentials hub provides directors with a single place to access clear, practical, and targeted resources to help them understand and meet their obligations with ASIC as a director,” ASIC Commissioner Kate O’Rourke said.
The hub includes guidance tailored to key stages of the director journey, including a roadmap to help directors navigate their obligations, from planning and setting up a company through to operating, restructuring or closing the business.
Directors can also access practical guidance for important situations, such as responding to financial difficulty, as well as free online learning modules that can be completed at any time.
The ATO is acquiring motor vehicle registries data from state and territory authorities from the 2026 to the 2030 income years.
The information will be matched against ATO records to identify taxpayers who are not meeting their registration, lodgment, reporting, or payment obligations across a number of taxes, including GST, FBT, fuel tax credits and income tax.
The data will also be used to support ATO compliance activities through modelling, risk profiling and case selection.
The data collected may include identification details for purchasers, sellers and other relevant parties, together with transaction dates and types, sale prices, market values, vehicle garage addresses, intended use, vehicle specifications and registration details.
The ATO expects to collect data relating to approximately 2.5 million individuals each financial year.
Under Payday Super, contributions must be received by an employee’s super fund within seven business days after payday.
To keep on track, the ATO recommends that employers:
For new employees, or where an employee changes their fund, employers generally have 20 business days to make the initial contribution.
The ATO is reminding businesses that Payday Super changes when super contributions must be paid, not who is entitled to receive them.
Businesses generally need to pay super where they engage an independent contractor mainly for their labour, personal effort, skills or time.
This can apply even if the contractor:
Where an independent contractor is entitled to super, the contribution must be paid for each payday and reach their super fund within seven business days after payday.
It is not mandatory to report payments made to independent contractors through Single Touch Payroll (‘STP’). However, if a business reports them voluntarily, it must meet the STP reporting requirements, including reporting qualifying earnings and super liability information.
The ATO has recently updated its Employees guide for work expenses to remind taxpayers that the new $1,000 standard deduction cannot be claimed for the 2026 income year.
From 1 July 2026, that is in respect of the 2027 income year and later years, employees may choose either the standard deduction for work-related expenses of up to $1,000, or a deduction for the actual work-related expenses they incur.
Taxpayers should continue keeping records for deductible work expenses incurred from 1 July 2026. If, at the end of the 2027 income year, they choose to claim their actual expenses, they must have the required written evidence for those expenses.
From 1 July 2027, the current 50% CGT discount is to be replaced with a new regime that distinguishes between gains accrued before and after that date. Under the legislated changes, gains accumulated up to 30 June 2027 will generally retain access to the existing 50% CGT discount, while future growth in value will be subject to the new indexation-based system.
For business owners, this means that understanding the value of your business as at 30 June 2027 may become increasingly important from a tax planning perspective. Establishing a supportable market value at that date can assist in identifying the portion of any future capital gain that may qualify for the existing 50% discount.
Wendy purchased her architectural practice in 2012 for $1 million. Through strong performance and growth, the business is worth $6 million at 30 June 2027.
The unrealised capital gain at that date is $5 million. Under the current rules, the 50% CGT discount would reduce this gain to $2.5 million (before considering any other available concessions).
The value of the business at 30 June 2027 effectively becomes a reference point, and maximises the tax benefit of the 50% discount. Any future increase in value after that date would be subject to the new post-2027 CGT rules.
Determining the market value of a private business can be highly subjective. A professionally prepared valuation can provide a well-supported and defensible basis for establishing value, helping to reduce uncertainty, and supporting your position should it ever be reviewed by the ATO.
At StewartBrown, our Partner Ray Itaoui is a CA Certified Business Valuation Specialist and can assist with independent business valuations across a wide range of industries.
While a valuation may assist with future tax planning, business owners often find significant value in obtaining an independent valuation for a range of other purposes, including:
If you would like to discuss how a valuation could assist your business or would like an obligation-free estimate of the likely cost, please contact us.
The Government has recently introduced legislation that would make the $20,000 instant asset write-off permanent for small businesses (as announced in the 2026 Federal Budget).
If enacted, the changes would:
The changes would also further suspend the 'lock-out rule' until 30 June 2027.
The Government has also recently introduced legislation to re-introduce the 'loss carry back' measure for companies from 1 July 2026.
If enacted, this will allow most companies to carry back a tax loss and apply it against tax paid in either, or both, of the previous two income years, basically giving rise to a tax refund for the loss year.
The ATO has identified that some taxpayers are incorrectly claiming rent, mortgage interest and other occupancy expenses as part of their work-from-home expenses.
To claim occupancy expenses, a taxpayer must be able to demonstrate that:
Factors that may indicate whether an area has the character of a 'place of business' include whether the area is:
Taxpayers who are eligible to claim occupancy expenses can claim a portion of those expenses based on floor area, the period they worked from home, and their ownership of the property.
Recently enacted legislation imposes new restrictions on the use of limited recourse borrowing arrangements ('LRBAs') by SMSFs.
LRBAs entered into on or after 10 August 2026 to purchase real property can now only be used to acquire business real property.
These changes do not apply if an SMSF:
'Business real property' generally means land and buildings used wholly and exclusively in one or more businesses.
The ATO is warning rental property owners that expenses shown in property manager reports may not always be classified correctly for income tax purposes.
Common issues identified by the ATO include:
The ATO has published a Division 7A benchmark interest rate of 8.77% for the income year ending 30 June 2027, up from 8.37% for the previous income year.
The ATO is obtaining Australian electoral roll information from the Australian Electoral Commission as part of its ongoing data-matching program.
The information will be compared with the ATO’s existing records to identify non-compliance with tax and superannuation obligations.
The data collected may include registered voters’ names, residential addresses, sex, dates of birth and occupations.
The ATO estimates it will receive records relating to approximately 18 million individuals each quarter.
The ATO has received concerning reports of a new email impersonation scam claiming to be from the ATO.
The email states that a phone appointment with the ATO has been scheduled and includes appointment details such as the date and time.
The email claims that recipients must open an attachment included in the email to securely access relevant services or reschedule the appointment.
The attachment contains a link to a legitimate looking myGov sign-in page designed to steal usernames, passwords and other personal information.
The ATO has confirmed that it will never:
The ATO has advised recipients not to respond to the email or interact with it in any way.
The Government has recently legislated several of the tax reform measures announced in the 2026 Federal Budget (and in later media releases). These include, among other things:
After a round of consultation, the Government has also announced further proposed measures, broadly including (among others):
The car limit for the 2027 income year is $69,883.
This is the highest value that a taxpayer can use to calculate depreciation on a car where they use the car for work or business purposes (and they first use or lease the car in the 2027 income year).
The maximum GST credit that can generally be claimed for the creditable acquisition of a car above the limit is $6,353 (i.e., one-eleventh of $69,883).
The luxury car tax ('LCT') threshold for the 2027 income year is $91,661 for fuel-efficient vehicles, and $80,809 for all other luxury vehicles.
The ATO is reminding business taxpayers of recent changes they should keep in mind this Tax Time, including the following:
Employers must also report both qualifying earnings and super liability through Single Touch Payroll ('STP') reporting.
If super is not received by the fund, in full and on time, the super guarantee charge applies.
The Government has announced a further temporary extension of fuel excise relief for July, together with a reduction in the Heavy Vehicle Road User Charge.
The Government says these measures will make petrol and diesel 16 cents per litre cheaper than they otherwise would have been during July.
The ATO is reminding taxpayers that they may have superannuation money held by the ATO. This can include:
Taxpayers can check for ATO-held super through myGov, ATO online services or the ATO app.
The ATO has added an extra verification step for super transfer and consolidation requests made through the ATO's online services.
This step is the latest ATO app security feature that helps protect against fraudulent activity.
If a taxpayer has registered their device using the ATO app, they will need to verify requests to transfer or consolidate super before the request is submitted (from May 2026).
The ATO nonetheless recommends that taxpayers review any real-time ATO app alerts, check their details, and act quickly if something looks wrong.
The Administrative Review Tribunal ('ART') recently considered whether an oral health therapist engaged by a dental clinic was an 'employee' for super guarantee purposes.
The clinic argued that the therapist was not an employee but was instead an independent contractor and, as such, the clinic was not liable for the super guarantee charge.
The ART disagreed, and held that the therapist was an employee under the extended definition.
In particular, the ART found that:
Please note: Many of the comments in this publication are general in nature. Anyone intending to apply the information to practical circumstances should seek professional advice to independently verify their interpretation and the information's applicability to their particular circumstances.
To assist us in the preparation of your 2026 Income Tax Return(s) we have prepared a brief checklist detailing the information we require. Please complete the checklist and return it to us, together with all the relevant documents and details requested. The checklist can be found here.
In an endeavour to complete your tax return(s) efficiently and to meet the lodgement deadlines, we ask that you forward your information to us as soon as possible. Before you do, please check it against last year’s return(s) for completeness. We also request that you attend to any queries raised by us during the preparation of the return(s) as quickly as possible.
The ATO is continuing its policy of conducting random tax audits to ensure compliance, and will impose penalties for errors and omissions in returns lodged. We remind you that the onus is on you, as the taxpayer, to ensure a detailed and accurate disclosure of income and expenses is made at all times. We strongly suggest that claims for rental property expenses and work related expenses be supported by the appropriate documentary evidence before you forward your information to us for the preparation of your return(s).
We have also prepared a summary of key issues to consider; the summary can be found here.
We would also like to bring to your attention our revised Engagement terms and Privacy Policy.
Should you have any doubts as to the assessability or deductibility of an item please provide us with the full details or contact this office and we will be pleased to assist you.
List of items to review:
The Partners of StewartBrown are delighted to announce the admission of Ray Itaoui as a Partner of the firm, effecive 1 July 2026.
Ray brings nearly 20 years of leadership experience across accounting and financial services. He is a Chartered Accountant, Chartered Business Valuation Specialist, Registered Tax Agent and SMSF Auditor, with extensive expertise in business advisory, business valuations, taxation, structuring and compliance. He is recognised for his practical and commercial approach to helping clients navigate complex financial and regulatory matters.
Ray’s appointment reflects the continued growth, strength and success of our firm. As StewartBrown continues to grow, it is critical that we continue to invest in leadership that brings fresh perspective, renewed energy, and new ideas to support our clients and our people. Ray’s elevation to Partner is a key part of that commitment.
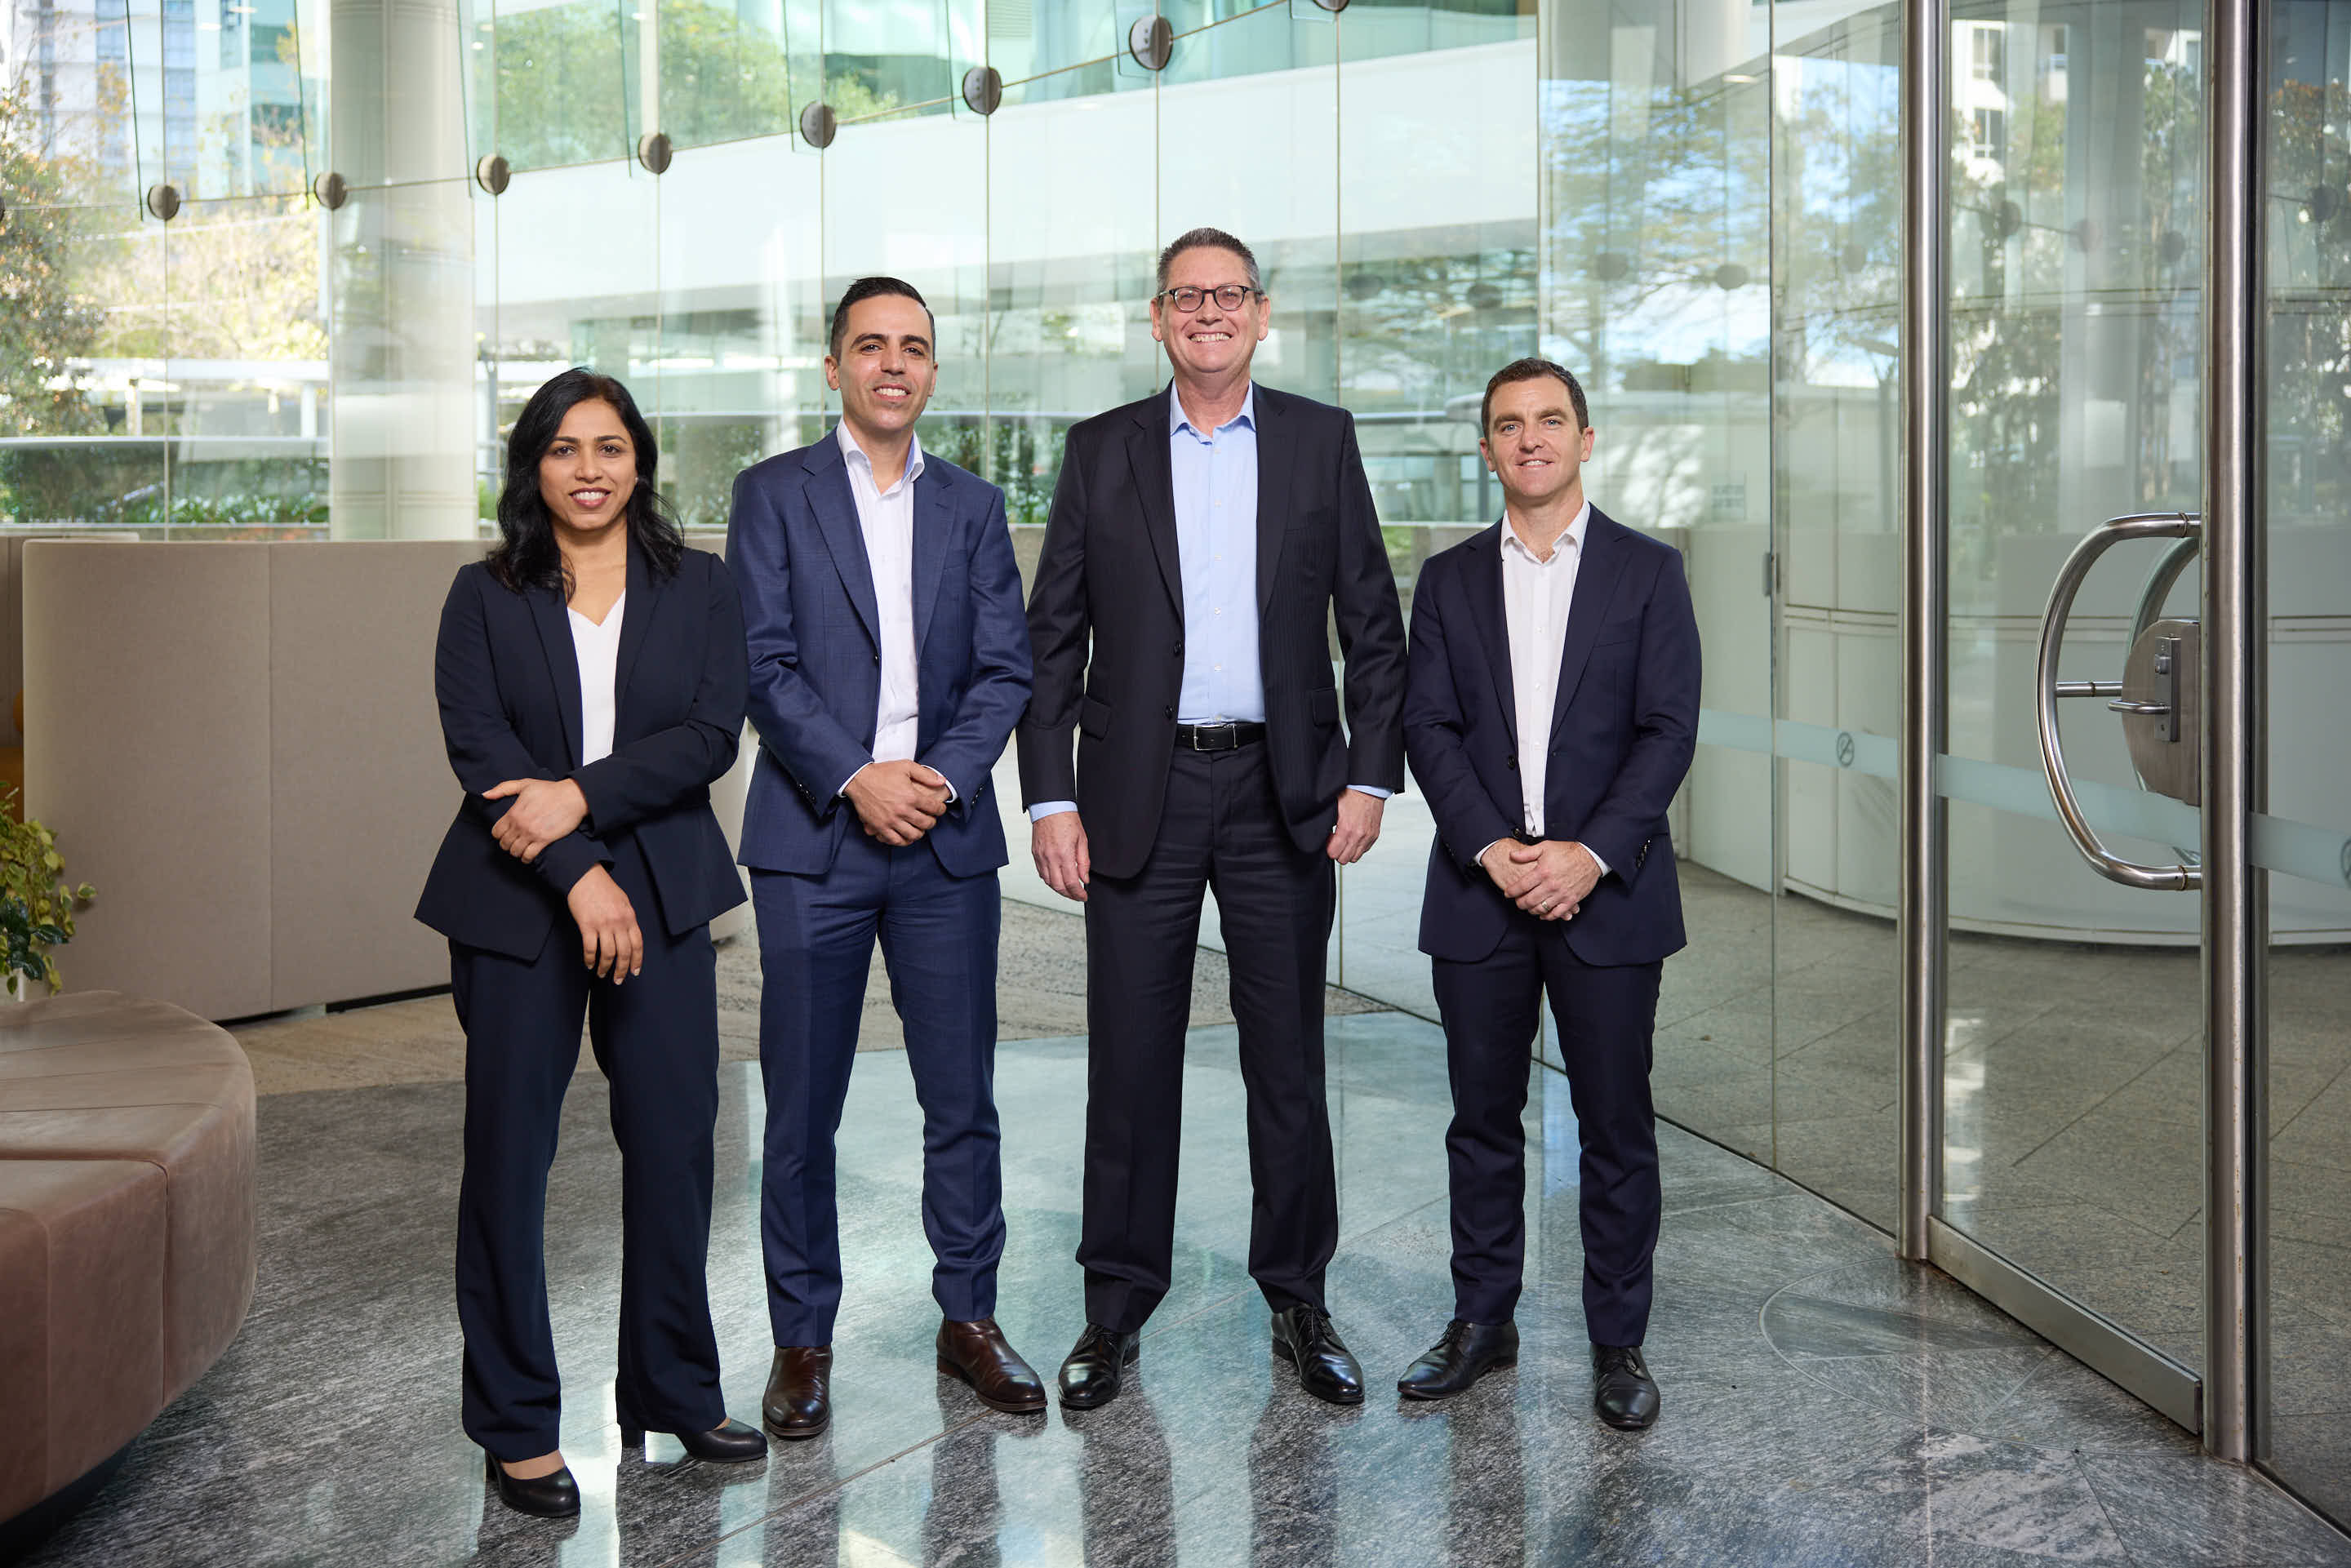
The StewartBrown Business Services Partners (from left to right, Bhavna Lathigara, Ray Itaoui, Russell McGree and Matthew Davie).
 As we approach the end of the 2026 financial year, it is an opportune time to review your tax position and consider strategies to optimise your outcome. Proper planning before 30 June can assist in maximising available deductions, managing cash flow, and ensuring compliance with ATO requirements.
From 1 July 2027, the 50 per cent Capital Gains Tax (CGT) discount will be replaced by cost base indexation for assets held for more than 12 months, with a 30 per cent minimum tax on net capital gains.
These changes will apply to all CGT assets, including pre-1985 CGT assets, held by individuals, trusts and partnerships. Transitional arrangements will limit the impact on existing investments by ensuring the changes only apply to gains arising on or after 1 July 2027. The 50 per cent CGT discount will continue to apply to gains arising before 1 July 2027. Capital gains on pre-1985 assets arising before 1 July 2027 will remain exempt from CGT. To maintain incentives for new housing supply, investors in new residential properties will be able to choose either the 50 per cent CGT discount, or cost base indexation and the minimum tax. Income support payment recipients, including Age Pension recipients, will be exempt from the minimum tax.
The Government will limit negative gearing for residential property to new builds. From 1 July 2027, losses from established residential properties will only be deductible against rental income or the capital gains from residential properties. Excess losses will be carried forward and able to be offset against residential property income in future years. These changes will apply to established residential properties acquired from 7:30PM (AEST) on 12 May 2026. Properties acquired prior to this time (including contracts entered into but not yet settled) will be exempt from the changes until disposed of. Eligible new builds will be exempt from the changes, ensuring the benefits of negative gearing are directed to investment that increases the housing stock. Properties in widely held trusts and superannuation funds will be excluded, alongside targeted exemptions for build-to-rent developments and private investors supporting government housing programs.
The Government will introduce a 30 per cent minimum tax on discretionary trusts to improve the fairness of the tax system and help fund new tax cuts for workers. From 1 July 2028, trustees will pay a minimum tax of 30 per cent on the taxable income of discretionary trusts. Beneficiaries, other than corporate beneficiaries, will receive non-refundable credits for the tax payable by the trustee.
The minimum tax will not apply to other types of trusts such as fixed and widely held trusts (including fixed testamentary trusts), complying superannuation funds, special disability trusts, deceased estates and charitable trusts. Some types of income such as primary production income, certain income relating to vulnerable minors, amounts to which non-resident withholding tax applies, and income from assets of discretionary testamentary trusts existing at announcement will also be excluded. The Government will provide expanded rollover relief for three years from 1 July 2027 to support small businesses and others that wish to restructure out of discretionary trusts into another entity type, such as a company or a fixed trust.
For tax years commencing on or after 1 July 2026, companies with aggregated annual global turnover of less than $1 billion will be able to carry back a tax loss and offset it against tax paid up to two years earlier. Loss carry back will apply to revenue losses only and will be limited by a company’s franking account balance.
The Government will also introduce loss refundability for small start‑up companies. For tax years commencing on or after 1 July 2028, start‑up companies with aggregated annual turnover of less than $10 million that generate a tax loss in their first two years of operation will be able to utilise the loss to generate a refundable tax offset. The offset will be limited to the value of fringe benefits tax and withholding tax on wages paid in respect of Australian employees in the loss year.
From 1 July 2026, the Government will permanently extend the $20,000 instant asset write‑off for small businesses with turnover up to $10 million. Assets valued at $20,000 or more can continue to be placed into the small business simplified depreciation pool. The provisions that prevent small businesses from re‑entering the simplified depreciation regime for 5 years after opting out will continue to be suspended until 30 June 2027.
The Government will also provide $10.9 million to the Australian Taxation Office to expand its pilot of dynamic pay as you go (PAYG) instalment calculations, and will expand access to monthly payments. From 1 July 2027, small and medium businesses will be able to opt in to reporting and paying PAYG instalments monthly and to using an ATO-approved calculation embedded in accounting software to calculate and vary their instalments. This will support businesses by enabling tax instalments to better reflect real time business activity. Taxpayers with a demonstrated history of non‑compliance will be required to report and pay PAYG instalments monthly.
The Government will deliver a new tax cut for every working Australian taxpayer by introducing a $250 Working Australians Tax Offset from the 2027–28 income tax year. The Working Australians Tax Offset will provide a permanent annual tax offset for Australians for their income derived from work, such as wages and salaries and the business income of sole traders, from 1 July 2027.
The Working Australians Tax Offset will increase the effective tax-free threshold for income derived from work by nearly $1,800 to $19,985 (or up to $24,985 for workers eligible for the Low Income Tax Offset).
The Government will introduce an instant tax deduction of up to $1,000 from the 2026–27 income tax year to make the tax system simpler while also delivering more cost-of-living relief. Australian tax residents who earn income from work will be eligible for the instant tax deduction and will not need to itemise and claim work-related expenses if claiming less than $1,000. Individuals who incur work‑related expenses greater than the instant tax deduction can continue to claim their deductions in the usual way. Charitable donations, union and professional association membership fees and other non-work-related deductions can still be itemised separately and claimed on top of the instant tax deduction.
Click here to view a detailed breakdown of all the tax reform additions and changes produced by Thompson Reuters
With less than two months until Payday Super starts (on 1 July 2026), the ATO wishes to 'clear up' the following common misconceptions.
Fact: Super funds should have already taken steps to receive more frequent contributions and meet shorter processing timeframes. System updates and testing should be underway, including implementing and testing for 'SuperStream Contributions v3.0' upgrades.
Fact: Payday Super raises expectations on speed, accuracy and responsiveness. It is not just about frequency — it is about how quickly and accurately contributions are allocated or rejected, within a tighter timeframe. Faster allocation and earlier rejection support employers to meet their obligations.
Fact: Super fund actions directly influence employer outcomes. They can support employer compliance by:
The ATO recognises that high fuel costs are affecting some businesses, and it will provide targeted support to eligible businesses that are unable to meet their payment obligations for three months, from 1 April 2026 to 30 June 2026.
In particular:
Businesses can assess their eligibility and notify the ATO of their interest in accessing a tailored payment plan and intention to vary PAYG instalments through the ATO's online services. The ATO will then contact these businesses or their representatives with more information and next steps.
The ATO has noticed some businesses have not updated their GST reporting and accounting methods after exceeding the relevant thresholds.
If a taxpayer's business has a GST turnover of $10 million or more, they need to use full BAS reporting instead of 'simpler BAS', and account for GST on a non-cash (accruals) basis.
If their business has a GST turnover of $20 million or more, they need to report GST monthly on their BAS instead of quarterly.
The ATO is moving some businesses to the correct GST reporting and accounting methods from 1 July 2026, although taxpayers can voluntarily make the switch now in 'Online services for business' on the ATO's website.
The Full Federal Court recently allowed the ATO's appeal against an Administrative Review Tribunal decision that a taxpayer was entitled to claim deductions for home office and car expenses.
The taxpayer worked full-time for the ABC as a sports presenter and producer. During the 2021 income year, because of COVID-19 pandemic restrictions, the taxpayer undertook one of his work roles from a second bedroom in his home apartment which he was renting with his wife. He undertook most of another work role from the ABC's Southbank Studios in Melbourne.
The Tribunal had allowed the taxpayer's deductions for occupation expenses (being a proportion of the rent for his apartment) and for car expenses (incurred in driving between his home and the ABC studio to perform his two roles) in full.
However, the Full Federal Court subsequently overturned this decision, noting (in relation to the claim for the occupation expenses) that the 'essential character' of the rent paid was to secure domestic accommodation, and the prevailing conditions requiring the taxpayer to work from home did not alter this.
Also, in relation to the car expense claims, the Court considered the taxpayer's travel between his home and the ABC studio was 'to work' rather than 'on work', and was therefore not deductible.
The Administrative Review Tribunal recently rejected an employee's claims for self-education expenses, as they did not have a sufficient nexus with his current job and income-earning activities.
The taxpayer worked as an employee for a large company. He claimed that his role evolved to include marketing and sales responsibilities during the 2022 income year, and that he was required to take courses in sales and marketing to help him perform his role.
The taxpayer sought to amend his tax return for the 2022 income year by claiming additional deductions for expenditure on online educational and training courses, related computer software and hardware, and membership fees.
The ATO disallowed these deductions, and the Tribunal affirmed the ATO's decision. The Tribunal noted that there was nothing in writing from the taxpayer's employer requiring him to undertake sales and marketing activities, let alone take self-education courses in those areas.
The expenditure incurred by the taxpayer related to online content creation, affiliate marketing, and entrepreneurship, whereas the taxpayer's work related to providing technical IT and computer services. Therefore, the expenditure did not bear a sufficient nexus with the taxpayer's income-earning activities for it to be deductible.
Taxpayers can now instantly confirm whether a call claiming to be from the ATO is genuine, with the launch of a new in-app security feature designed to shut down scammers.
The new verify call feature allows users to confirm, in real time, that they are speaking with the real ATO, not a fraudster.
Taxpayers are encouraged to download the ATO app and register their device. Then, when they receive a call from someone claiming to be from the ATO, they can simply open the ATO app, login and select the verify call option.
Within 30 seconds, a notification should confirm it is an ATO call. If it does not appear, users should treat it as a scam call and hang up.
Parliament has now passed legislation introducing an additional tax on superannuation earnings for individuals with large super balances. These measures are commonly referred to as the Division 296 tax and will affect members with total superannuation balances above certain thresholds.
Below we outline the key features of the new rules and what they may mean for you.
The start date has been deferred, with the new tax now applying from 1 July 2026. This provides additional time for super funds, trustees and members to prepare.
The tax will apply to realised earnings only, rather than year to year changes in account balances.
In practical terms:
The legislation introduces a graduated approach:
Trustees of small superannuation funds (including SMSFs) will be able to elect to reset the cost base of fund assets to their market value as at 30 June 2026, for Division 296 purposes only.
Key points to be aware of:
For affected clients, we recommend considering the following in advance of 30 June 2026:
If a member has a total superannuation balance of $4.5 million and the fund earns $500,000 in 2026–27:
Please give our friendly team a call with any questions.
If you would like advice tailored to your personal circumstances, our financial planning division, StewartBrown Advisory, offers comprehensive advice on SMSFs, retirement planning and investments.
From 1 July 2026, major changes to superannuation obligations, known as ‘payday super’, will take effect for all employers. The new timeframes and contribution processes apply to all employers, including companies, sole traders, partnerships, and trusts. These changes mean that super guarantee contributions must now be paid and received by your employees’ super funds within seven days of each payroll cycle. Super will be calculated on employees’ Qualifying Earnings (payment for ordinary hours of work plus any salary sacrifice super amounts). This article outlines the practical steps your business should take to remain compliant and ensure a seamless transition.
The new rules require super payments to reach employees’ super funds within seven days after processing payroll, rather than the previous quarterly deadlines. To meet these stricter timelines, it is crucial to review and adjust your cashflow management. Consider forecasting super obligations for each pay run, maintaining a buffer in your accounts, and scheduling payments to align with payroll dates. Proactive planning will help avoid late payments and potential penalties.
With the introduction of payday super, your payroll software or system must be capable of processing and remitting super contributions promptly after each pay cycle. Review your current payroll processes and consult with your provider to ensure your system is configured for the new payment frequency. It’s also a good time to test automated super payments and ensure that reporting aligns with the updated requirements.
The SBSCH will permanently close on 1 July 2026. If your business currently uses the SBSCH to process super payments, you will need to transition to an alternative super clearing house or direct payment method. Before the closure, download and securely store all historical super payment records from the SBSCH for your compliance files. Investigate other clearing house options early to avoid disruption and ensure your new provider can meet the seven-day payment requirement.
Effective onboarding of new team members is more important than ever. When bringing on new staff, ensure you offer a choice of super fund and clearly explain the default fund option if they do not nominate their own. Accurate and timely onboarding will help avoid delays in setting up super contributions, ensuring compliance from day one.
The shift to payday superannuation requires careful preparation. Adjust your cashflow processes, confirm your payroll system is ready, transition away from the SBSCH, and update your onboarding procedures. Taking these steps now will help your business stay compliant and support your employees’ retirement savings. For more tailored advice, please contact our office for a review of your payroll and superannuation processes.
StewartBrown
ABN: 63 271 338 023
Level 2, Tower 1,
495 Victoria Avenue
Chatswood, NSW, 2067
Stewart Brown Advisory Pty Ltd
ABN: 19 143 011 750
AFSL: 355134
Level 2, Tower 1,
495 Victoria Avenue
Chatswood, NSW, 2067
StewartBrown
ABN: 63 271 338 023
Level 2, Tower 1,
495 Victoria Avenue
Chatswood, NSW, 2067
Stewart Brown Advisory Pty Ltd
ABN: 19 143 011 750
AFSL: 355134
Level 2, Tower 1,
495 Victoria Avenue
Chatswood, NSW, 2067